Download: Rho Analysis PDF
Objective#
Find a risk parameter ρ that predicts drawdown — so Lab 9B can use it to size down during dangerous periods and size up during high-conviction ones.
The Four Candidates#
| Candidate | Definition | Hypothesis |
|---|---|---|
| ρ₁ | Rolling price variance | Higher vol → larger drawdown |
| ρ₂ | Volume-weighted price variance | Vol-adjusted vol is a better risk signal |
| ρ₃ | HMM entropy H(γ) | Regime uncertainty → poor signal quality |
| ρ₄ | Variance of Bull signal returns | Dispersed outcomes → risky? |
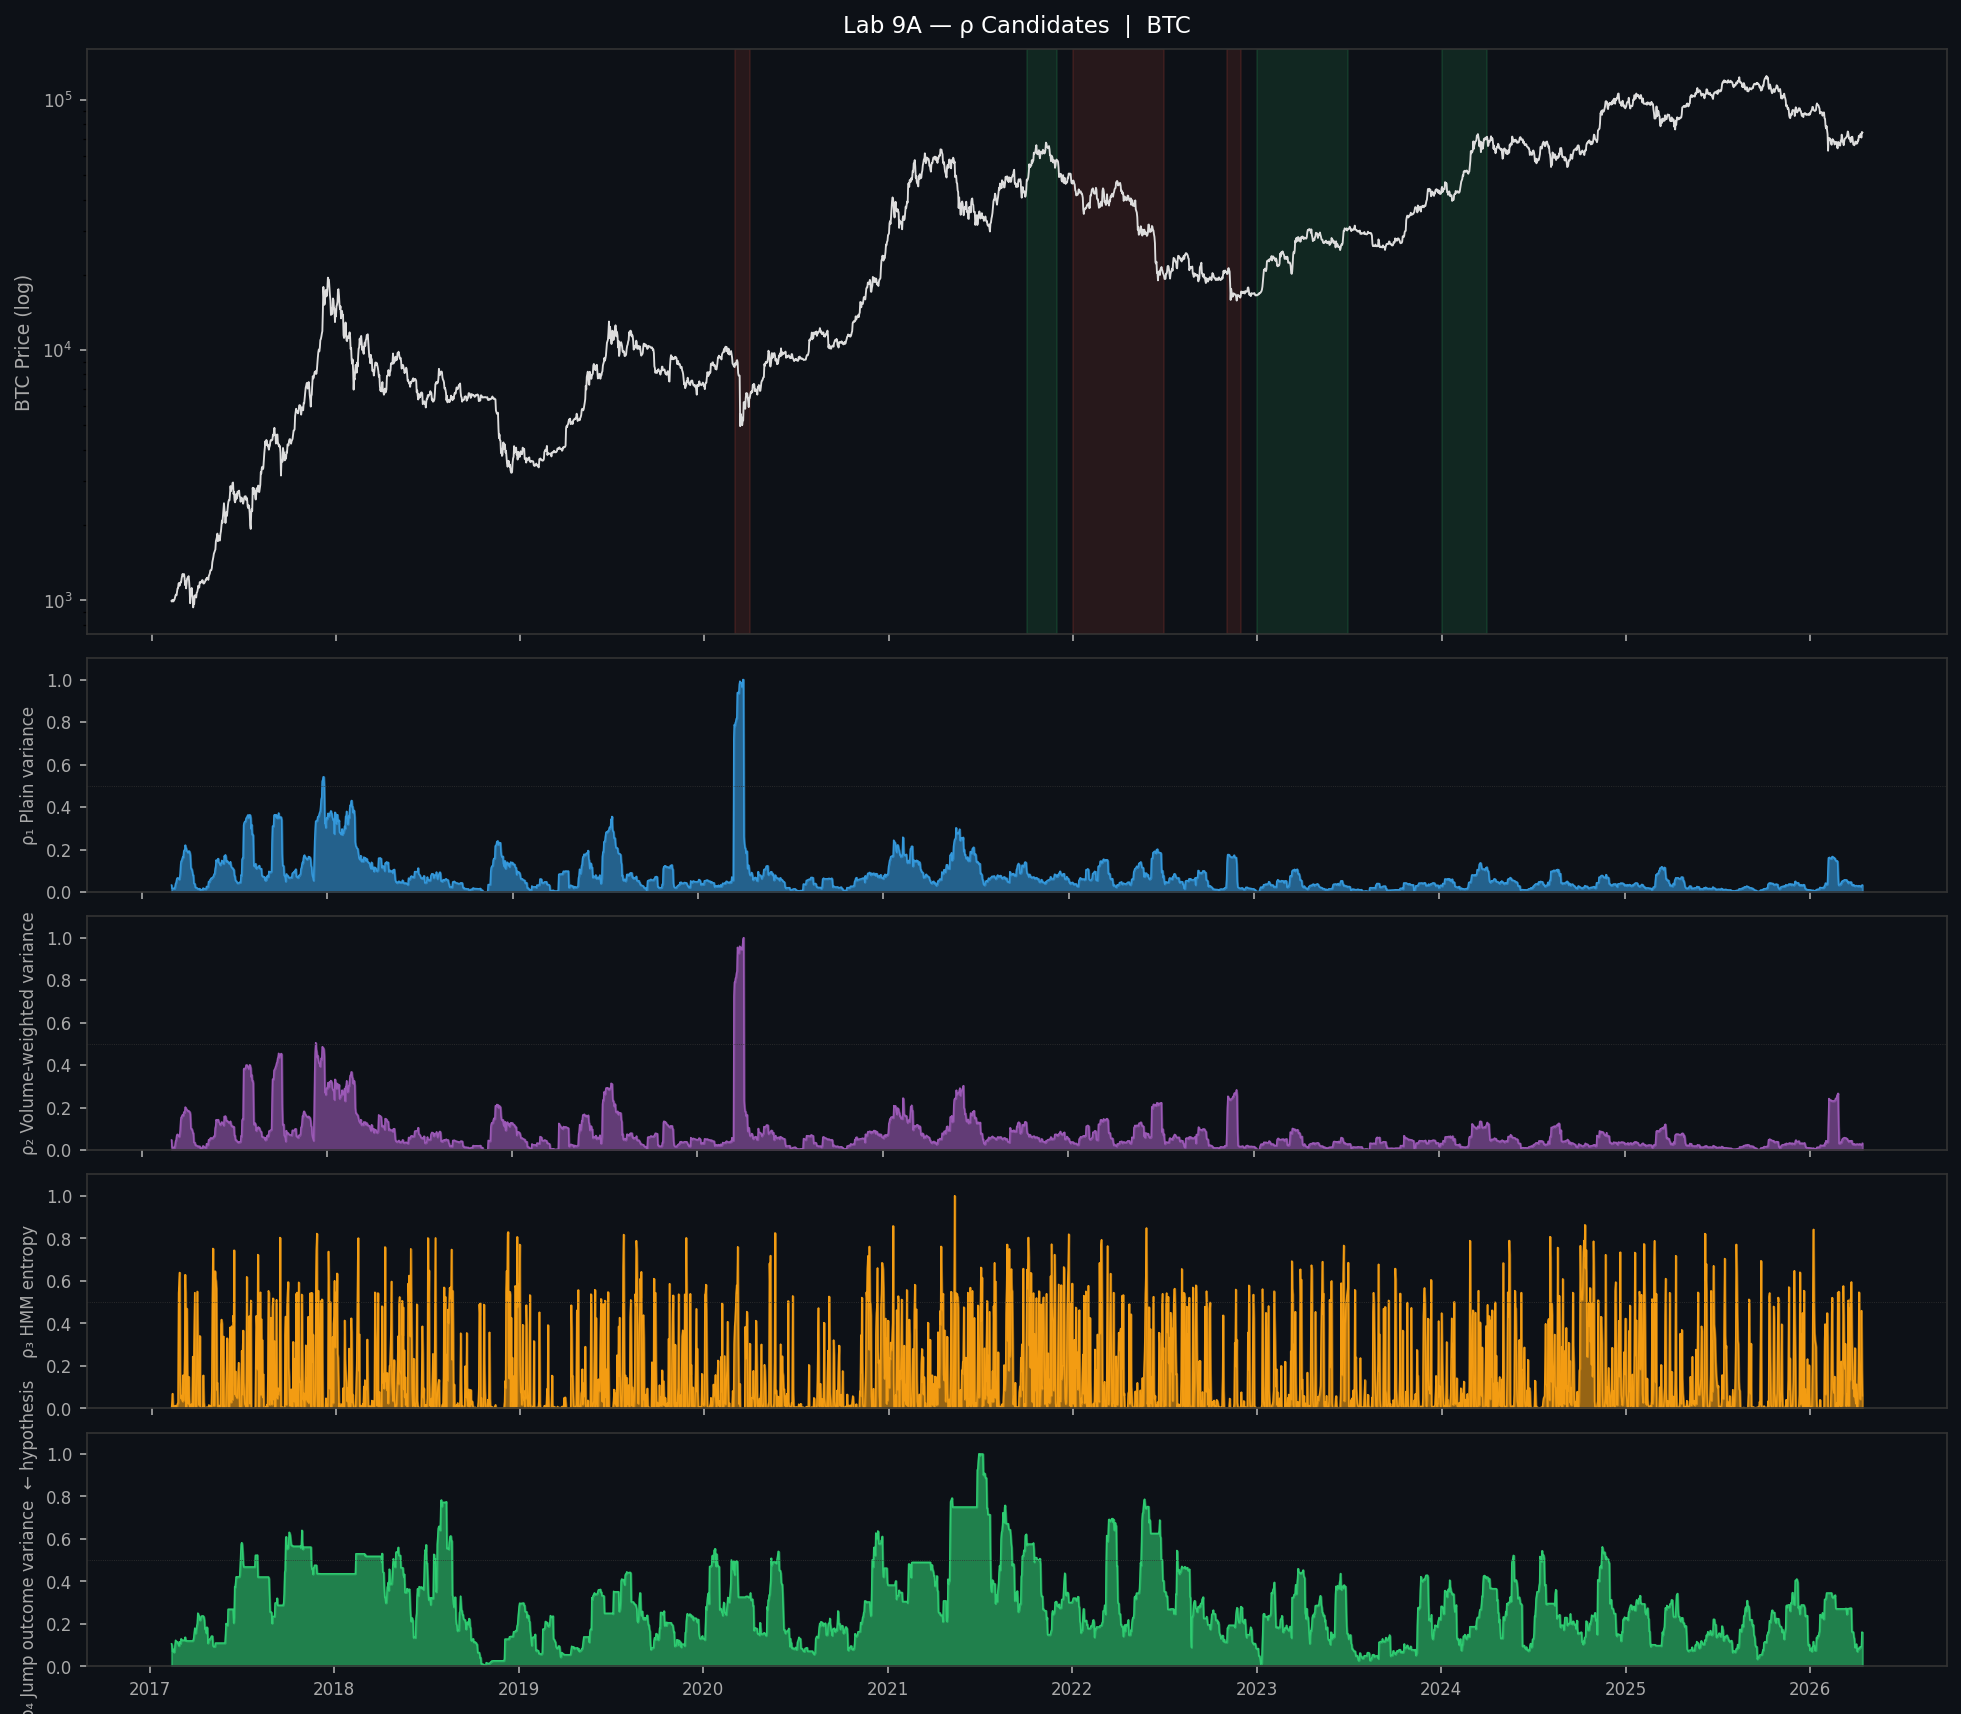
Results — BTC#
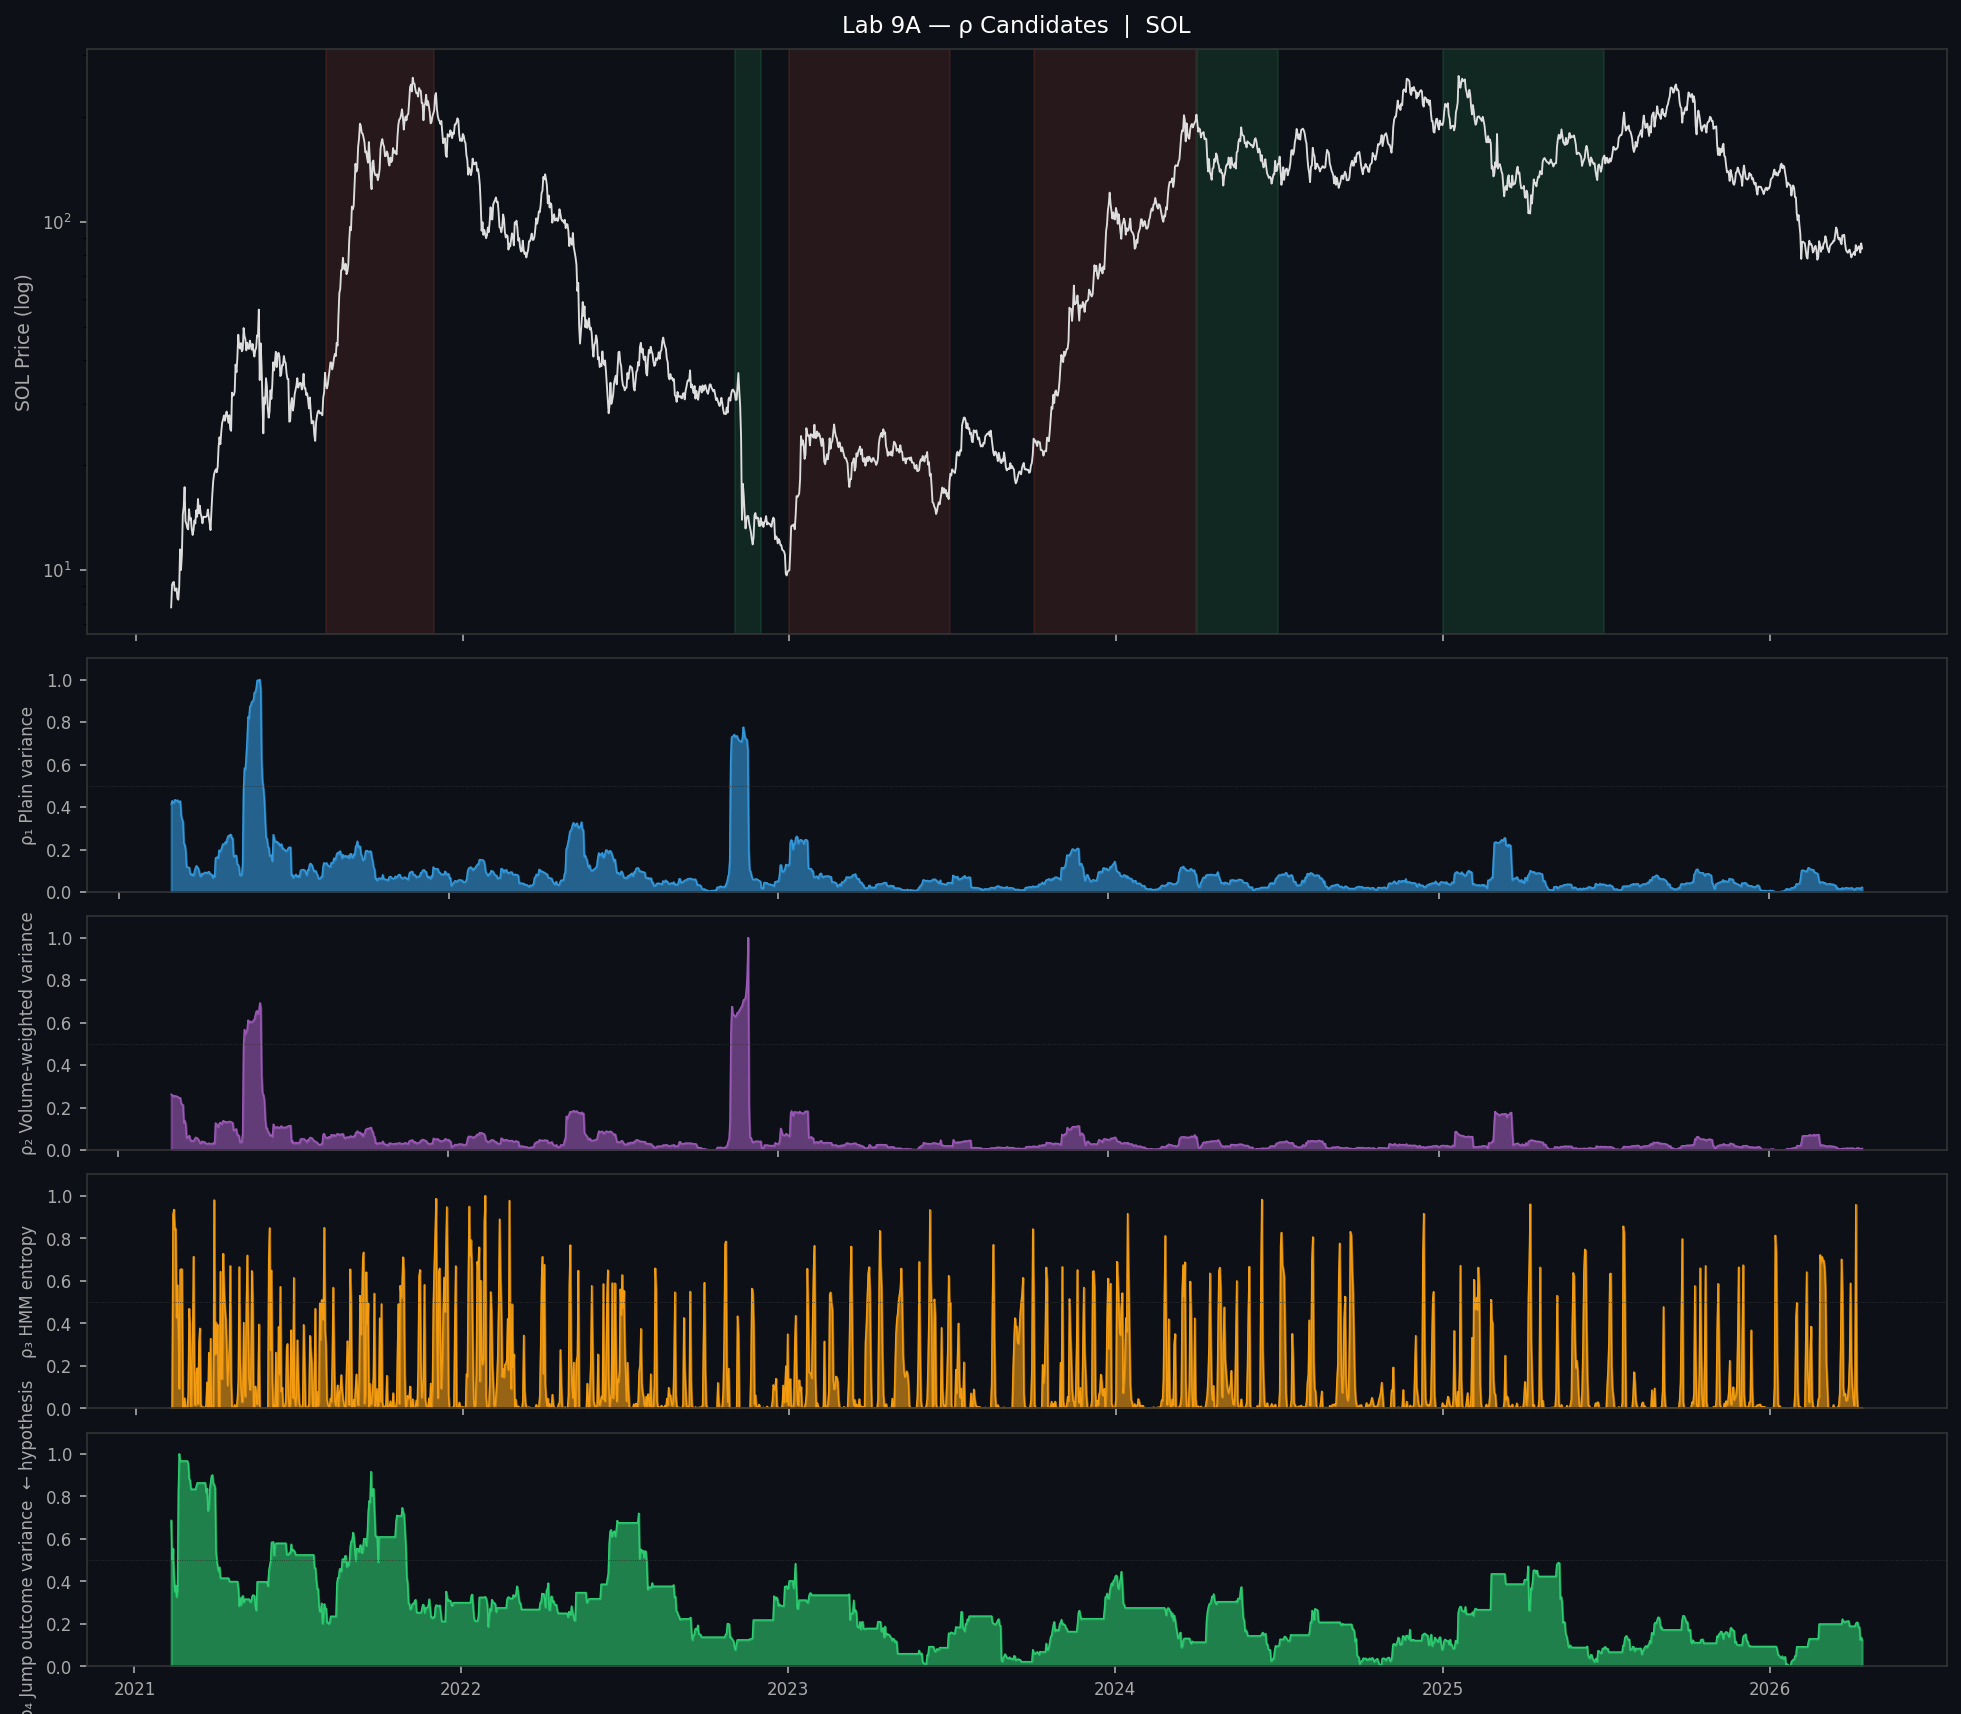
Results — SOL#
Key Discovery#
ρ₄ is negatively correlated with drawdown. This is the opposite of the hypothesis.
When Bull signals fire frequently with dispersed returns, the market is trending hard — the strategy is winning repeatedly even if individual trade sizes vary. Drawdown is low because there’s momentum.
This inverts ρ₄’s role entirely:
| Candidate | Use as |
|---|---|
| ρ₁ | Risk floor / Kelly denominator |
| ρ₂ | Slightly better risk floor |
| ρ₃ | Signal quality filter (skip trades when entropy > threshold) |
| ρ₄ | Conviction signal — size UP, not down |
Implication for Lab 9B#
The dual-input sizer design:
size = f*(ρ₁) × scale(ρ₄)Where f* is the ρ₁-based Kelly fraction and scale(ρ₄) amplifies when conviction is high.