Objective#
Test whether HMM regime posteriors γ_k(i) from Lab 4 improve directional prediction vs. alpha factors alone.
Model#
- Features: Alpha factors (rolling returns, z-score, volume ratio) + γ_k(i) posteriors from Lab 4 HMM
- Target: Next-bar direction (binary)
- Model: XGBoost classifier
- Validation: Temporal split — BTC test set Jun 2024 – Apr 2026; SOL $10k sim Jan 2023 – Apr 2026
Results — BTC Accuracy#
| Model | Accuracy | Sharpe |
|---|---|---|
| Baseline (alpha only) | 51.7% | −3.33 |
| Lab 5 (alpha + regime) | 56.3% | −3.03 |
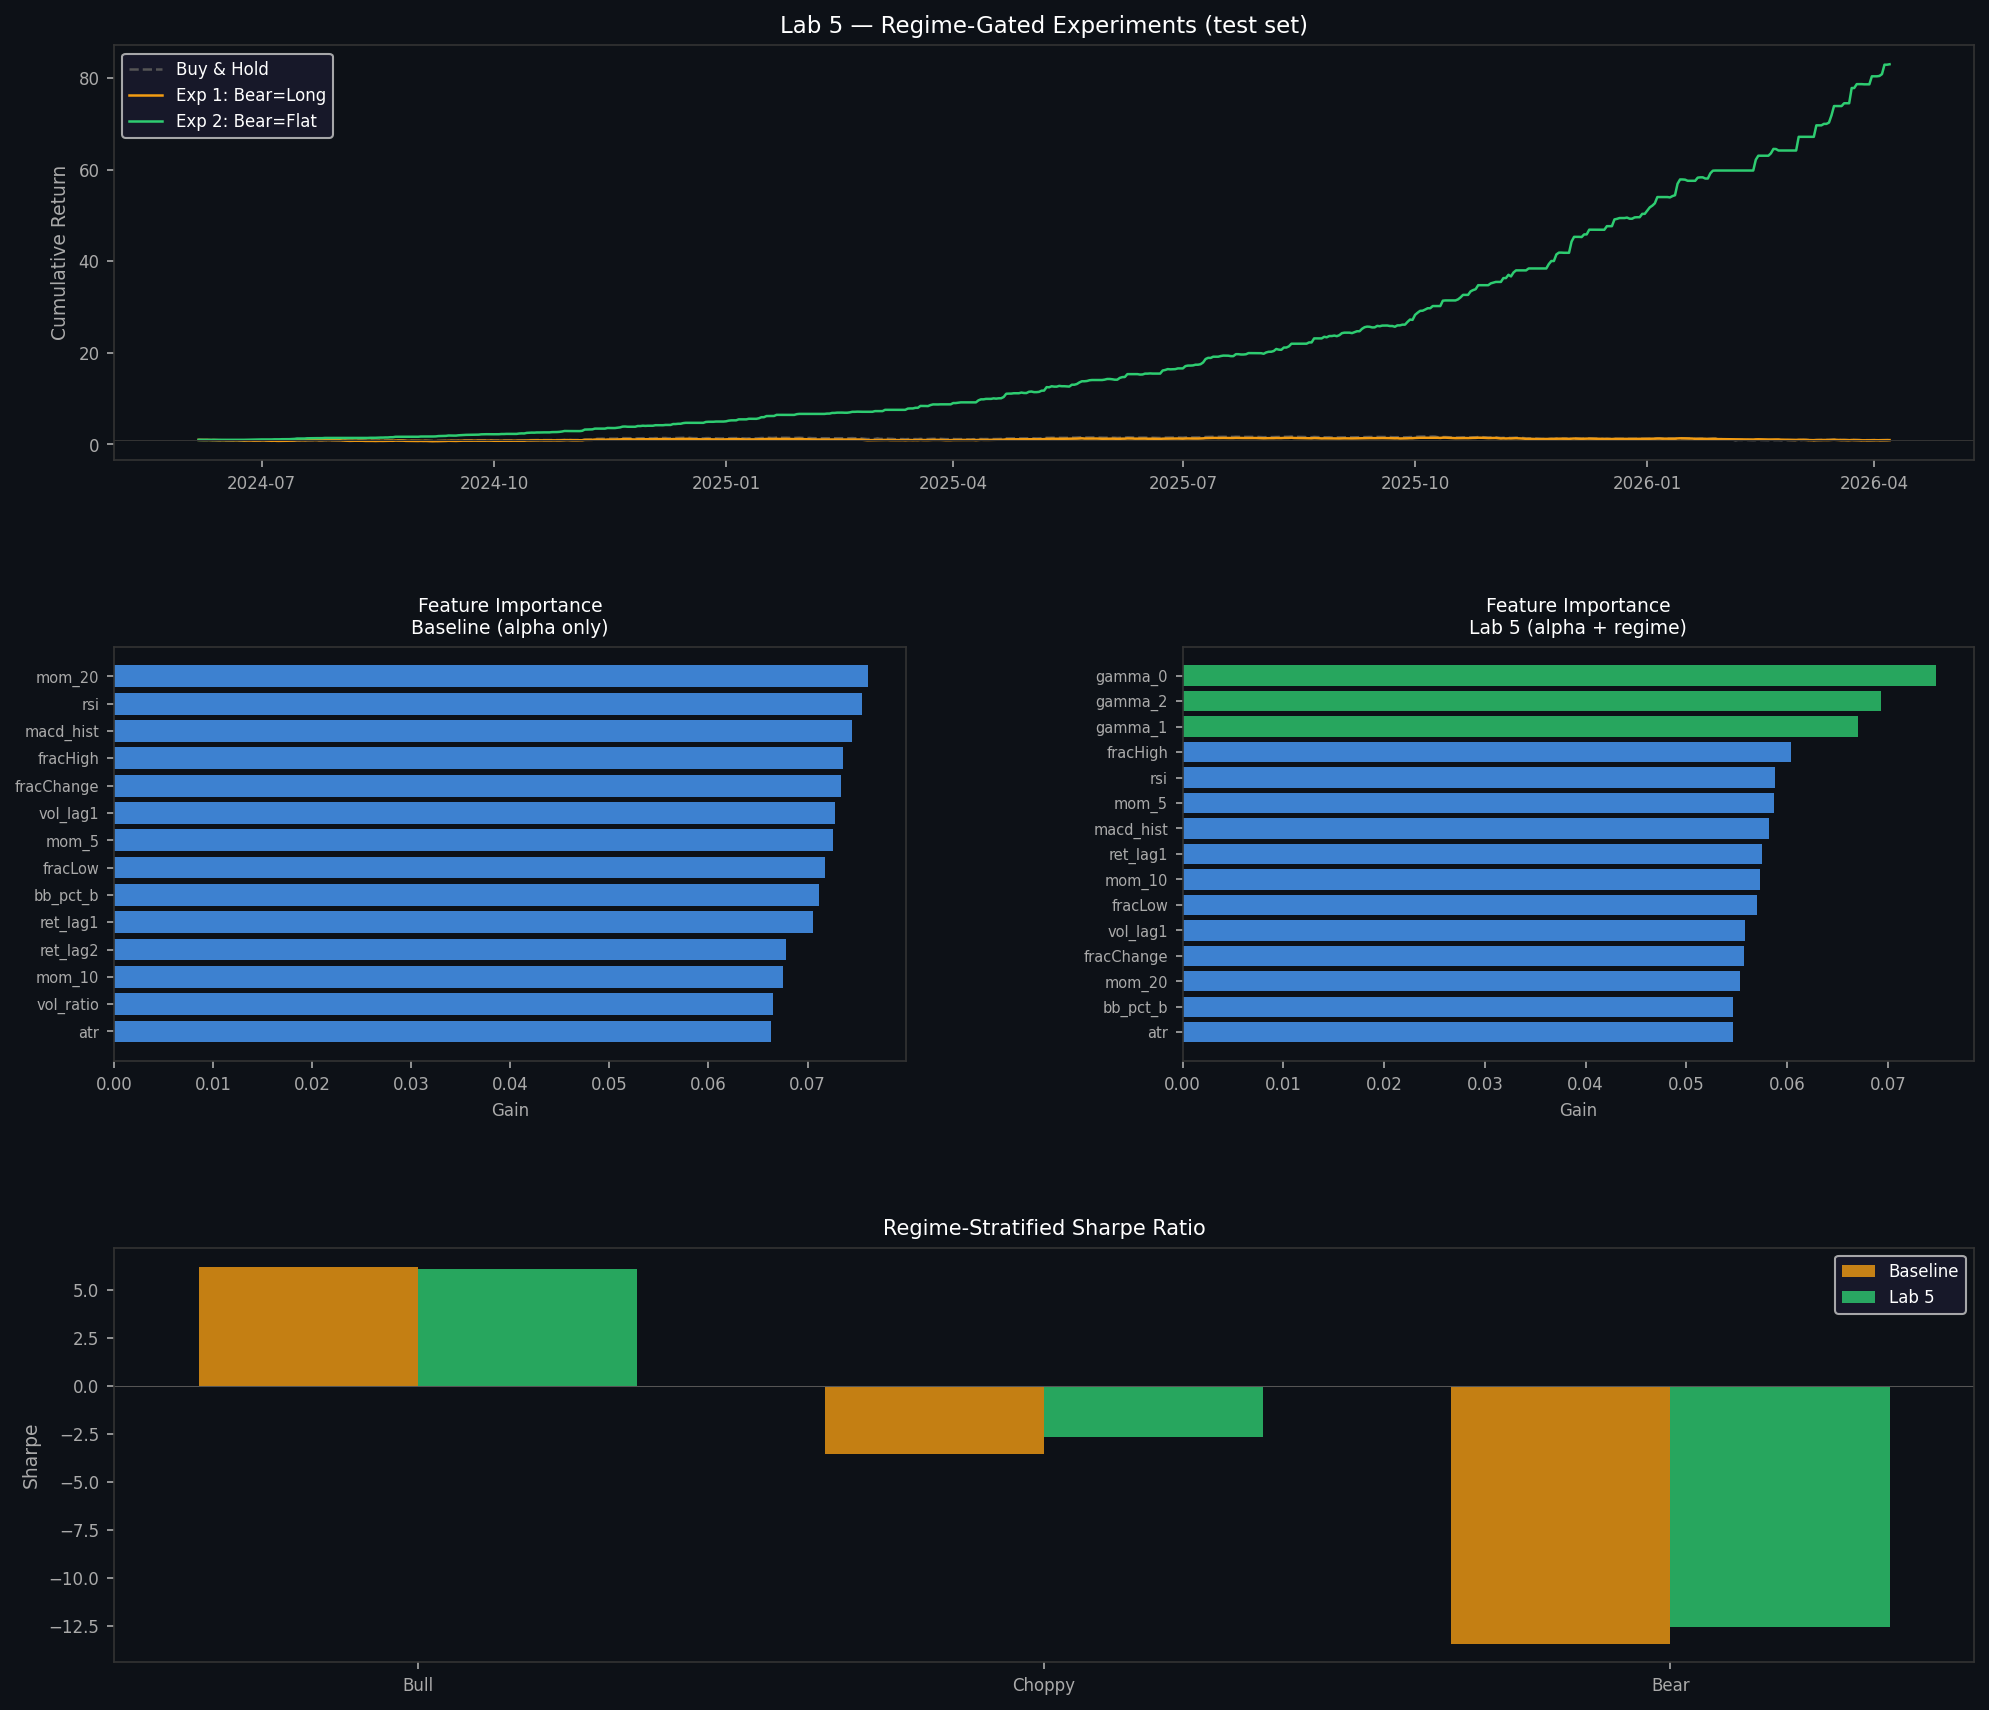
Regime posteriors add +4.6pp accuracy and +0.30 Sharpe lift.
Results — Regime-Gated Strategy (BTC)#
| Strategy | Sharpe |
|---|---|
| Buy & Hold | −0.03 |
| Bull=Long, Bear=Long | −0.07 |
| Bull=Long, Bear=Flat | +8.21 |
Key finding: Sitting out during Bear regimes is the entire edge. The signal doesn’t need to be right — it needs to know when to do nothing.
Results — SOL Simulation ($10k)#
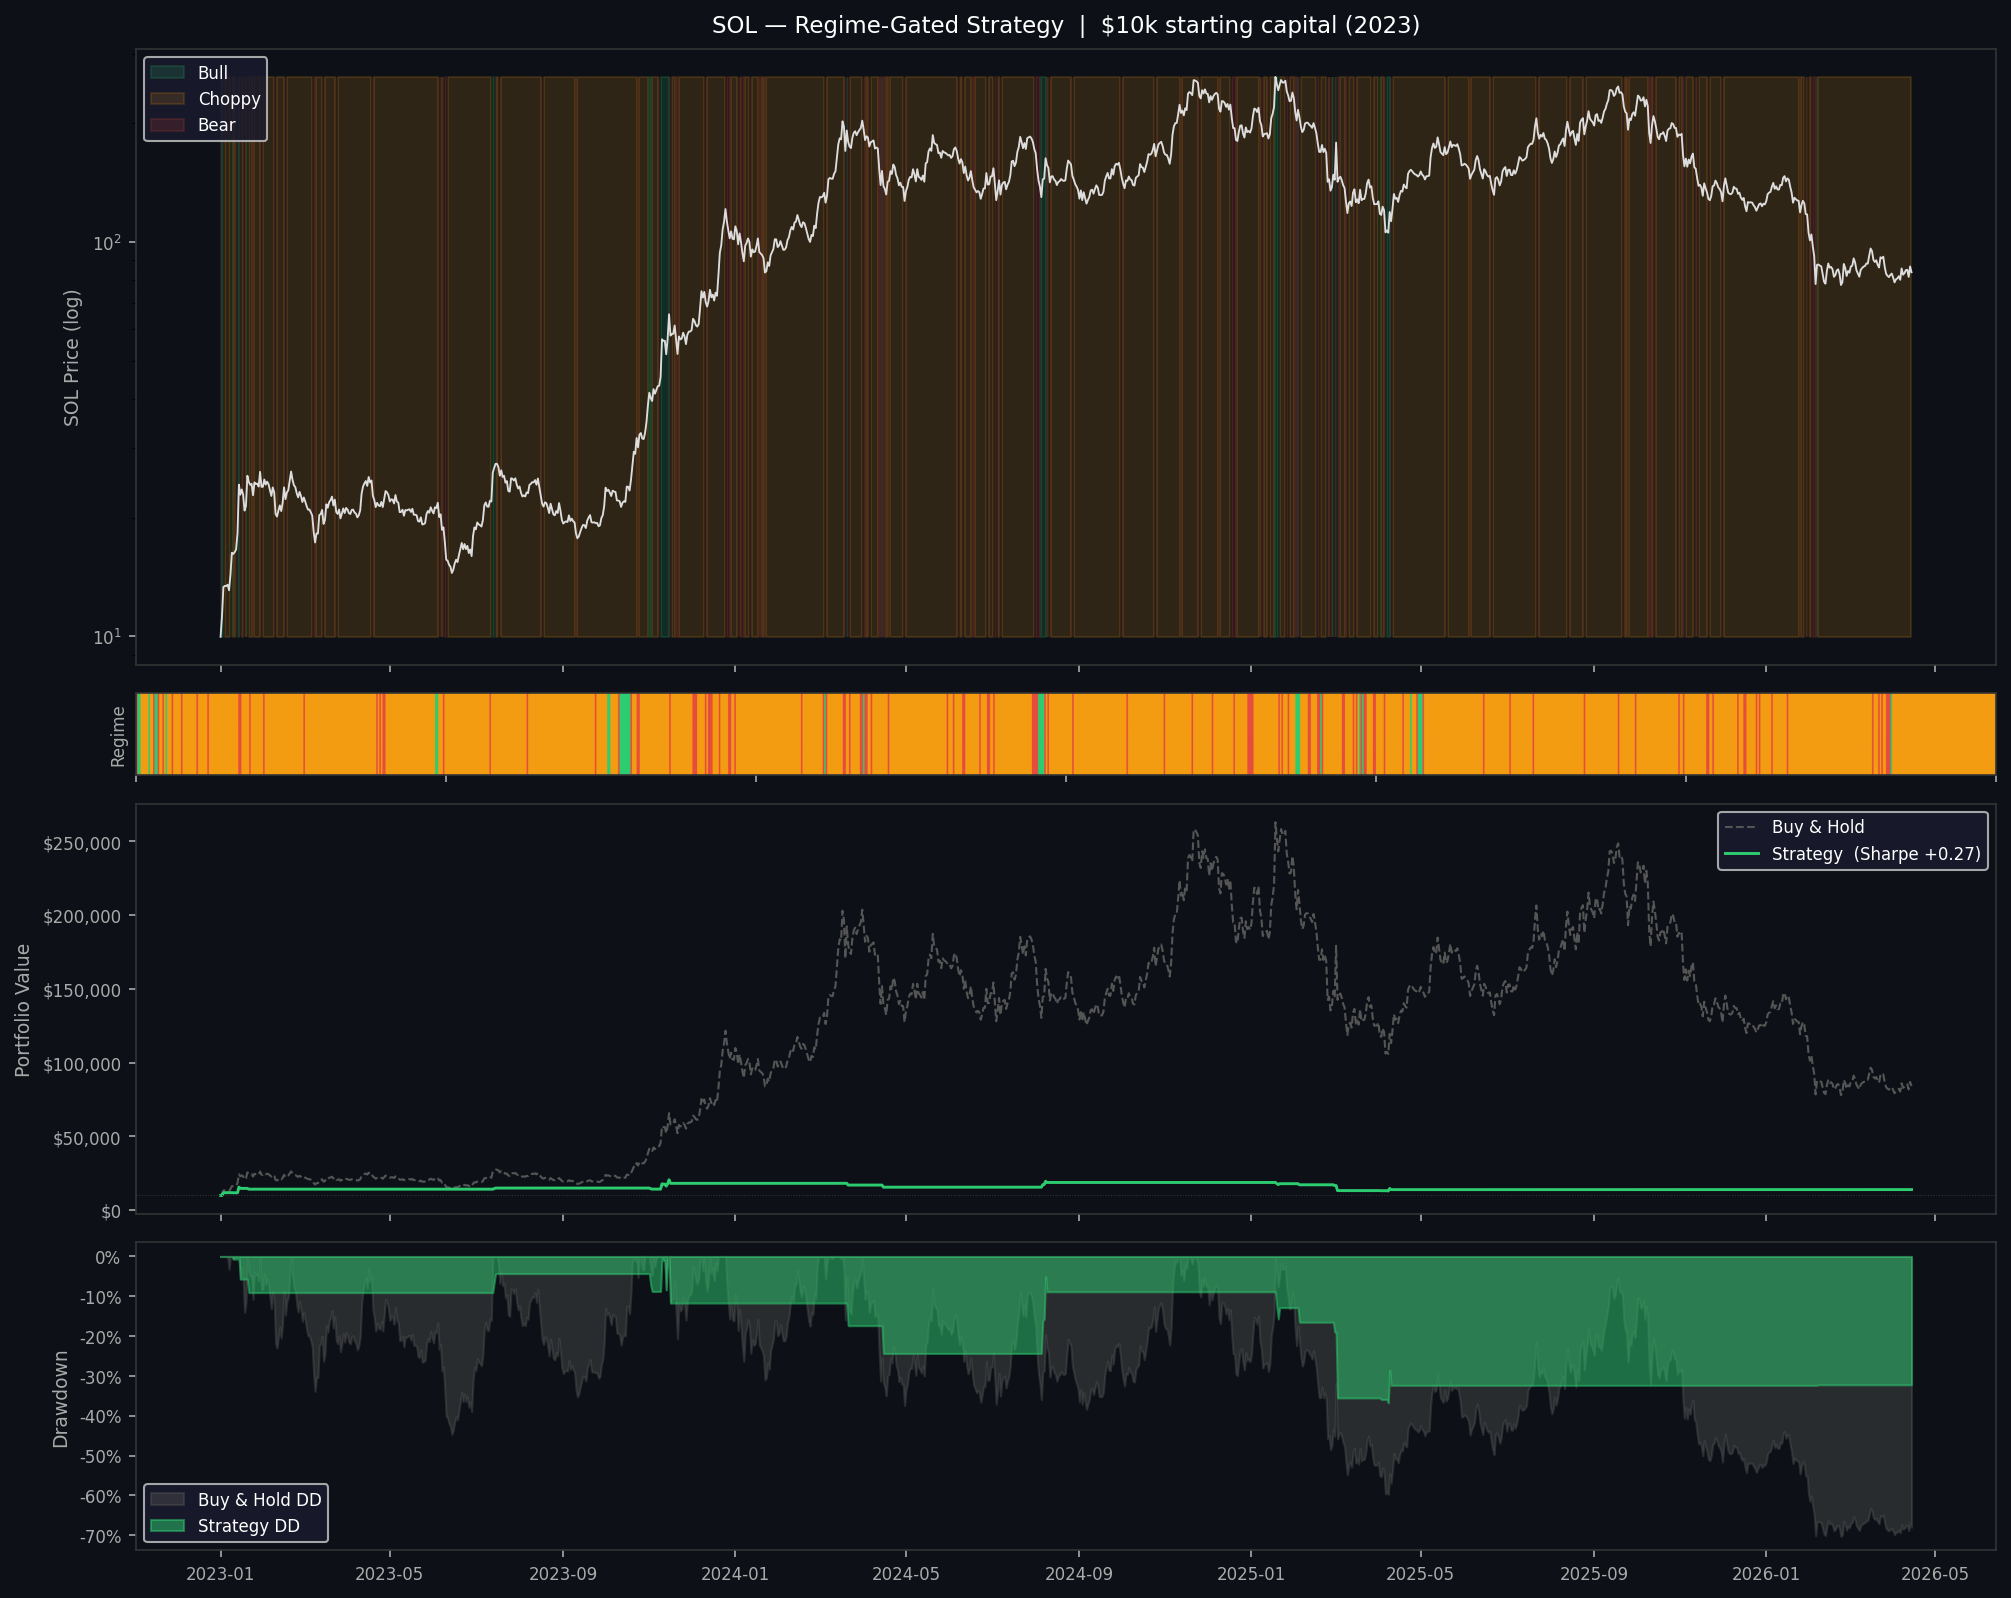
SOL simulation: $10k → $14k with regime gating. HMM was trained on BTC — Lab 6 fixes the SOL-specific calibration.